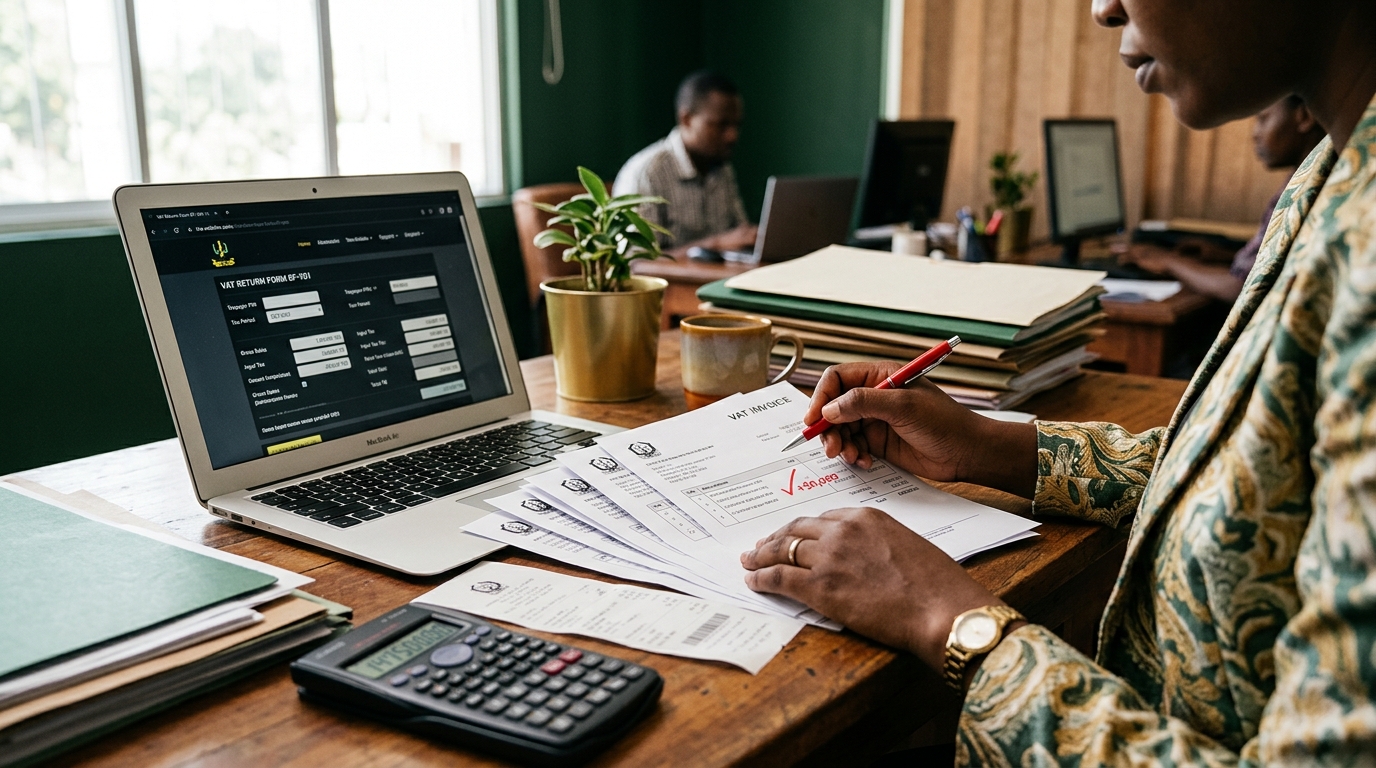
VAT is one of the taxes Tanzanian businesses deal with most often, and also one of the easiest to get wrong. Most penalties we see don’t come from complex disputes. They come from small, repeated slips in the monthly routine. Here are the most common ones and how to avoid them.
1. Filing late, or not filing at all
VAT returns are monthly and are due by the 20th day of the following month. That applies even when you had no sales: a nil return is still a return. Missing the date triggers penalties and interest, and repeated late filing draws TRA’s attention.
Avoid it: put the 20th in your calendar for the whole year, and aim to file a few days early so system issues don’t catch you out.
2. Claiming input VAT without proper receipts
You can only claim input VAT on purchases backed by a valid tax invoice or EFD/VFD receipt that shows your TIN. Supplier receipts without your details, lost receipts or handwritten invoices are routinely disallowed during audits.
Avoid it: ask every supplier for a fiscal receipt with your TIN at the point of purchase, and file receipts monthly, not at year end.
3. Mixing up exempt, zero-rated and standard-rated supplies
The standard VAT rate is 18%, but some supplies are zero-rated and others are exempt. These are not the same: zero-rated supplies still let you recover input VAT, while exempt supplies generally don’t. Getting the category wrong affects both the VAT you charge and the VAT you can claim back.
Avoid it: list your main products and services and confirm the VAT treatment of each once, then build it into your invoicing system.
4. Returns that don’t match the books
TRA compares your VAT returns with your EFD data, your income tax return and your financial statements. Differences between them, even innocent timing differences, are a common audit trigger.
Avoid it: reconcile sales per the VAT return to your EFD Z-reports and your general ledger every month before you file.
5. Weak record keeping
Tax law requires you to keep records that support your returns, generally for at least five years. If you can’t produce the invoice, contract or receipt behind a figure, expect it to be challenged.
Avoid it: keep a simple monthly VAT file (digital or paper) with the return, the reconciliation and all supporting invoices.
The bottom line
Good VAT compliance is mostly routine: file on time, collect proper receipts, know your VAT categories and reconcile before you submit. If you’re unsure whether past returns are correct, a short VAT health check can find issues before TRA does.
This article is general information, not tax or legal advice. Rules change and every business is different, so speak to an STAA advisor about your situation.